Last Updated: October 26, 2026
Quick Summary
Uninsured window cleaners expose you to serious financial liability if they get injured on your property or damage your home. You may be responsible for their medical bills, lost wages, repair costs, and legal fees, potentially reaching tens of thousands of dollars.
- Request a certificate of insurance and verify it directly with the insurer before hiring.
- Confirm the policy covers ladder work and work at height, as many policies exclude these activities.
- A minimum of $1 million in general liability coverage is standard for residential window cleaning.
- If the contractor has employees, they must carry workers’ compensation insurance.
- Call 911 immediately if an injury occurs and notify your homeowner’s insurer promptly, even if no claim has been filed.
Table of Contents
- Why Uninsured Window Cleaners Put You at Financial Risk
- How to Verify a Contractor’s Insurance Before Hiring
- Understanding Certificate of Insurance for Contractors
- Workers’ Compensation for Window Cleaners: What You Need to Know
- What Happens When an Uninsured Window Cleaner Gets Injured on Your Property
- Questions to Ask a Window Cleaning Company About Coverage
- Schedule Your Free Consultation with a Fully Insured Professional
- Frequently Asked Questions
Why Uninsured Window Cleaners Put You at Financial Risk
Hiring an uninsured window cleaner might seem like a smart way to save money upfront. When something goes wrong, you could face serious financial consequences.
If an uninsured contractor gets injured on your property, you may be liable for their medical bills, lost wages, and legal fees. If they damage your home or a neighbor’s property, you’re on the hook for repairs. These costs can easily reach tens of thousands of dollars.
The risks of hiring uninsured window cleaners extend beyond a single accident, affecting your homeowner’s insurance, your credit, and your peace of mind.
How to Verify a Contractor’s Insurance Before Hiring
Before you hire any window cleaning company, you need concrete proof they carry proper insurance. Don’t take their word for it, request documentation and verify it directly.
Ask for a certificate of insurance. This document shows the contractor’s coverage and policy limits. A legitimate contractor will provide it without hesitation; refusal or evasion is a red flag.
Call the insurance company directly. Use the insurer’s contact information on the certificate to confirm the policy is active, don’t rely on a document that could be outdated or fraudulent.
Check the policy limits. A $300,000 limit may not cover a major incident. For residential window cleaning, you want at least $1 million in general liability coverage.
Verify the contractor is the policyholder. Some contractors use someone else’s policy or are listed only as an additional insured. Know who actually carries the coverage.
Ask about workers’ compensation. If the contractor employs workers, they need workers’ compensation insurance to cover on-the-job injuries. Without it, you could be liable.
Look for gaps or exclusions. Ask whether the policy covers window cleaning at heights, ladder work, and high-rise properties, since many policies exclude these activities. Learn what specific contract terms to check regarding insurance coverage and contractor qualifications.
OSHA guidelines on contractor safety and liability
Understanding Certificate of Insurance for Contractors
A certificate of insurance (COI) is a one-page summary a contractor’s insurer or agent issues to show what coverage exists at a point in time.
What the certificate shows. The standard form lists the named insured, insurer and NAIC number, policy number, policy period, coverage types, and limits.
Read the dates, not just the limits. A certificate with a policy period that ended last month proves nothing about today.
Match the coverage to the work. $1 million per occurrence and $2 million aggregate are a common residential benchmark, but what matters more is whether the policy covers the specific activity. Ask whether it includes window cleaning, ladder work, and work above a stated height, since many policies exclude work at height or require a separate endorsement.
Confirm workers’ compensation separately. If the contractor has employees, the certificate should show a workers’ compensation line with a policy number and limits. If it’s missing, the contractor either has no employees or no coverage, know which.
Distinguish uninsured, underinsured, and improperly insured. These are not the same problem, and the difference changes your exposure:
- Uninsured: No policy exists. Any injury or damage claim points at you or the cleaner personally.
- Underinsured: A policy exists but its limits are low relative to the job. A $300,000 limit can be exhausted by a single serious fall, leaving the excess for you to argue about.
- Improperly insured: A policy exists but does not cover this work, this worker, this location, or this claim. Examples include a policy that excludes ladder work, a policy written for a different business entity, or a workers’ compensation policy that does not list the crew actually on your property.
Improperly insured is the hardest to spot because the contractor can truthfully say “I have insurance.” The certificate alone won’t always expose the gap, which is why the next step matters.
Verify, don’t just file. Understand essential contract clauses and compliance requirements that protect against uninsured contractor risks. Call the insurer or agent using a number you look up independently, not the one printed on the document.
Ask about additional insured status. Being named as an additional insured on the contractor’s general liability policy can give you direct access to that coverage if a claim arises.
Keep the paper trail. Save the certificate, verification email or call notes, and any contract language about insurance. If a dispute arises later, this record shows you took reasonable steps to confirm coverage.
When you look for professional window cleaners for your business, request this document from every contractor before signing any agreement.
Workers’ Compensation for Window Cleaners: What You Need to Know
Workers’ compensation insurance protects employees if they get injured while working, essential for window cleaners, whose job involves real risks.
How it works: If a window cleaner employed by a contractor gets hurt on your property, workers’ compensation should cover their medical treatment and a portion of lost wages. Without it, they might sue you instead.
Not all window cleaners are employees. Some are independent contractors, and the distinction matters legally. An independent contractor might carry their own insurance, or nothing at all, know which applies.
Requirements vary by state. Most states require contractors to carry workers’ compensation if they employ workers, though some have exceptions for very small operations. Regardless, insist on proof of coverage.
The contractor should provide proof. Like general liability, workers’ compensation coverage comes with documentation, ask to see it.
Missing workers’ compensation is a major red flag. If a contractor says their workers are independent contractors, ask those workers whether they carry their own insurance. If they don’t, you’re dealing with an uninsured situation.
An uninsured window cleaner who gets injured might sue you, claiming your property was unsafe or that you negligently hired an uninsured contractor. These lawsuits are expensive to defend, even if you win.
What Happens When an Uninsured Window Cleaner Gets Injured on Your Property
A window cleaner falls from a ladder, slips on a wet sill, or suffers heat illness on a summer job.
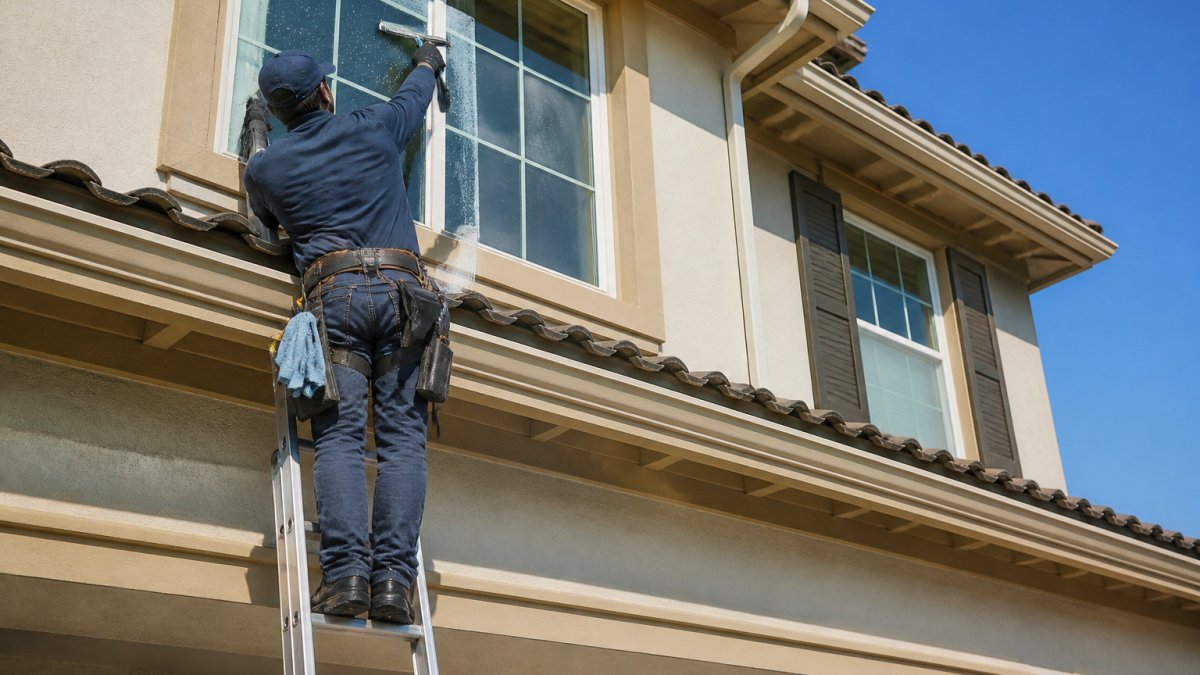
First, emergency care. Call 911 if the injury is serious. Do not move an injured person who may have a spinal injury unless they are in immediate danger.
Second, secure the scene without destroying evidence. Don’t move the ladder, hose, bucket, or other equipment until photos are taken, unless it’s blocking emergency access.
Third, document. Photograph the scene and equipment without interfering with care, and write down the time, what you saw, and who said what, memory fades and details matter later.
Fourth, notify your homeowner’s insurer promptly. Most policies require prompt notice of any incident that could lead to a claim, even if none has been filed.
Fifth, do not admit fault or promise payment. Sympathy is appropriate; admissions are not. A statement like “don’t worry, I’ll cover it” can be used against you later.
Sixth, preserve the contract and the certificate. If you have a written agreement and a certificate of insurance, keep them.
What the injured cleaner may do next. If uninsured, they may pursue you directly for medical bills, lost wages, and rehabilitation, a serious fall can produce bills well into five figures. They may also allege negligent hiring or an unsafe property. Even a defense you win costs money.
What your homeowner’s policy may and may not do. Many homeowner policies exclude injuries to workers hired by the homeowner, expecting the worker’s own coverage to respond.
The distinction in practice. An uninsured cleaner has nothing behind them. An underinsured cleaner has a policy that may cover part of the loss but not all.
Even if you believe the cleaner was careless, you can still face a claim. Proving their negligence does not automatically end your exposure, and defending the claim has its own cost.
Reduce the risk before it happens. Verify a certificate of insurance before work begins, confirm the policy covers ladder work and work at height, and put the insurance requirement in writing in the contract. If the contractor can’t produce proof, postpone the work. That single step prevents most of the scenario above.
Questions to Ask a Window Cleaning Company About Coverage
Before you hire anyone to clean your windows, ask these specific questions about their insurance and liability protection.
“Can you provide a current certificate of insurance?” This is your first and most important question. If they hesitate or make excuses, find someone else.
“What are your general liability policy limits?” Listen for a number. A minimum of $1 million is standard for residential work. Anything less is concerning.
“Does your policy cover ladder work and work at height?” Some policies exclude these activities. You need explicit confirmation that your job is covered.
“Are you carrying workers’ compensation insurance?” If they have employees, this is non-negotiable. If they’re a solo operator, ask if they carry coverage anyway.
“Will you add me as an additional insured on your policy?” This provides extra protection. Many contractors will do this at no extra cost.
“What happens if something gets damaged during the cleaning?” Their insurance should cover accidental damage to your property. Confirm this explicitly.
“How long have you maintained this insurance?” A contractor who just got insurance to make a sale is riskier than one with a long history of continuous coverage.
“What exclusions or limitations does your policy have?” Read the certificate carefully, some policies have surprising gaps.
“If I get injured while you’re working, what coverage applies?” This shouldn’t happen, but it’s good to understand the liability chain.
State contractor licensing and insurance requirements (requirements vary by state and jurisdiction)
Get accurate window cleaning quotes that include detailed insurance information.
Schedule Your Free Consultation with a Fully Insured Professional
Hiring the right window cleaner means protecting yourself financially and legally. The risks of hiring uninsured window cleaners are too high, one accident can create thousands in liability your homeowner’s insurance won’t cover.
When you’re ready to move forward, work with a contractor who takes insurance seriously. Our technicians undergo rigorous classroom and on-the-job training, and we hold monthly safety meetings to ensure every job is done right.
We also offer virtual quote options.
Schedule a free quote with Simply Superior Window Cleaning today.
| Risk Type | What It Covers | Your Potential Liability |
|---|---|---|
| General Liability | Property damage, third-party injury | Repair costs, medical bills, legal fees |
| Workers’ Compensation | Employee injuries on the job | Medical expenses, lost wages, rehabilitation |
| Uninsured Contractor | Nothing | Full cost of injury, damage, legal defense |
| Underinsured Contractor | Limited coverage | Amount exceeding policy limits |
Frequently Asked Questions
What happens if an uninsured window cleaner gets injured on my property?
Always verify that your window cleaning contractor carries proper workers’ compensation insurance before work begins.
How can I verify that a window cleaning company has insurance?
Request a certificate of insurance directly from the contractor before scheduling work. This document shows the policy holder, coverage types, policy limits, and expiration dates. Contact the insurance company listed on the certificate to confirm the policy is active. Never accept verbal assurances or photos of certificates; request official documentation from the insurance provider.
Can I be held responsible if a window cleaner damages my home?
Yes. If an uninsured cleaner damages your property or a neighbor’s property, you may be liable for repair costs. Your homeowner’s insurance may deny claims if the contractor was uninsured or improperly classified. Property damage from uninsured cleaners can include broken windows, damaged siding, gutter damage, or roof leaks. Costs can easily exceed $5,000 to $15,000 for significant damage. Hiring a properly insured, licensed contractor protects you from these expenses and ensures the contractor’s insurance covers accidental damage.
What should I ask a window cleaning company about insurance before hiring?
Ask for their general liability coverage limits, workers’ compensation policy details, and whether they carry coverage for high-rise or ladder work if applicable. Request the certificate of insurance. Ask how long they’ve maintained continuous coverage.